 A toothache has an unfortunate way of interrupting everything else. When a dentist recommends a crown, root canal, or another procedure, the next concern may be how to pay for it. Canadians exploring practical borrowing options for an unexpected dental expense should begin by understanding the recommended treatment, available coverage, and the full price rather than choosing financing under pressure. A good decision supports your health without creating a payment problem that lasts long after the appointment.
Ask What the Treatment Plan Actually Includes
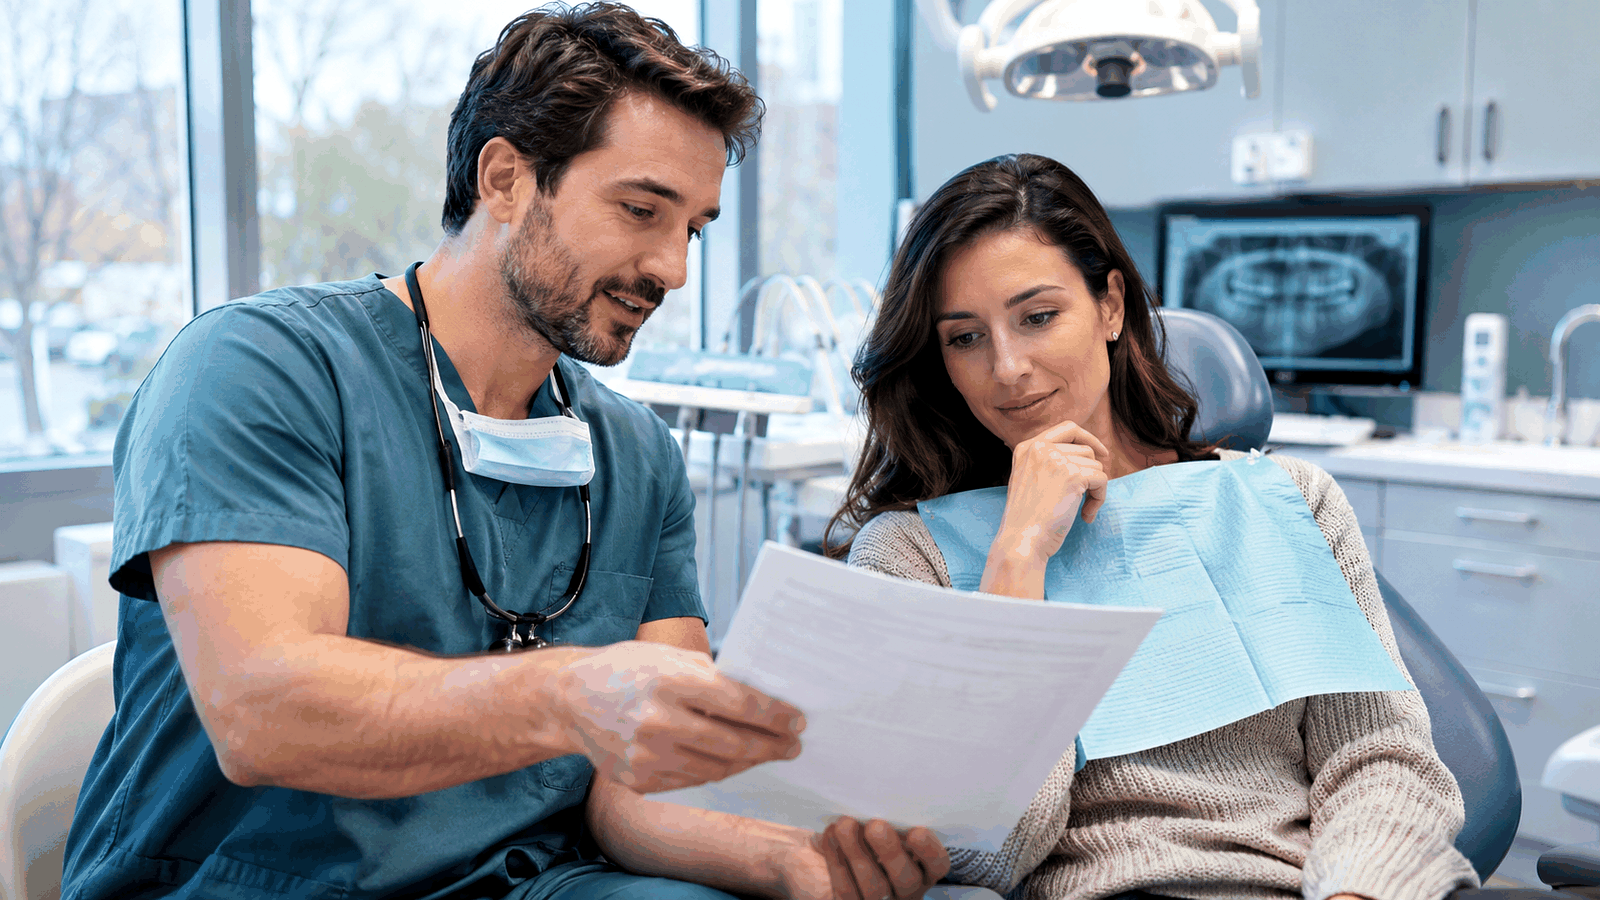
A dental estimate can contain several separate services: an examination, X-rays, laboratory work, materials, specialist fees, and follow-up visits. Ask the clinic for a written treatment plan that separates these components and explains what is essential. If a procedure is urgent, ask what risks come with waiting. If it is elective or can safely be scheduled later, the extra time may allow you to save or compare prices. A second clinical opinion may be worthwhile for major non-emergency work, particularly when several treatment paths exist. Do not postpone urgent care merely to avoid discussing its cost; instead, have the cost conversation early.
Check Every Possible Source of Coverage
Employer dental benefits, a partner’s plan, provincial programs, and the federal Canadian Dental Care Plan may cover certain services for eligible patients. Eligibility, exclusions, coordination rules, and coverage amounts vary. Contact the plan administrator or review the actual benefit details rather than assuming the full invoice will be reimbursed. A dental office may be able to submit a predetermination so you can estimate your portion before work begins. Ask whether the provider bills an insurer directly and whether an uncovered balance is due on the appointment date. Keep copies of estimates, benefit responses, and receipts.
Compare the Cost of Timing and Payment Methods
Some dental practices offer staged treatment or installment arrangements. Ask whether these carry interest or administrative charges, and get the terms in writing. If a credit card is considered, check its rate and how much of the balance could realistically be paid before interest accumulates. A personal loan may have a different repayment structure, but the quoted interest rate is only part of the comparison: include all applicable fees and the total amount to be repaid. A lower monthly payment can become more expensive if it lasts much longer. Never assume that a lender will approve an application or release funds within a particular timeframe.
Fit the Payment Into Ordinary Life
List your take-home income and essential expenses before agreeing to installments. Include housing, groceries, utilities, transportation, medications, and existing debt payments. Leave room for variable costs rather than committing every remaining dollar. If income fluctuates, use a conservative monthly estimate. Consider what happens if the final invoice differs from the initial estimate or an additional appointment is needed. Borrow only for costs you understand and can manage, and preserve enough cash for daily necessities. When a proposed payment leaves no room for ordinary surprises, it may not be the right financing arrangement.
Keep Medical Urgency Separate From Sales Urgency
Being worried about a painful tooth can make any immediate solution appealing. A responsible financing decision should still allow time to read the contract and ask about repayment dates, late charges, cancellation rights, and any credit checks. Be cautious of promises of guaranteed approval, demands for unusual advance payments, or unclear lender identity. Verify the provider and the terms for your province. If a family member offers help, establish whether the arrangement is a gift or a loan and discuss expectations openly. The goal is to solve a health problem, not exchange it for avoidable financial stress.
Make the Next Appointment Easier to Fund
After the immediate issue is addressed, review how routine dental care fits your annual budget. Preventive visits, cleanings, and smaller repairs may be easier to finance through monthly savings than a sudden large invoice. Even modest deposits into a dedicated health-expense category can build a buffer. If the treatment involved debt, prioritize the agreed payments while planning future appointments around available resources. Good dental decisions depend on medical guidance; good financing decisions depend on complete costs and realistic repayment. Considering both together creates a stronger outcome than rushing to borrow first and asking questions afterward.